I have worked Southern California commercial real estate for more than two decades, and the San Gabriel Valley is the market I know street by street. Here is how the current quarter reads from inside a deal rather than from the top of a research report.
Industrial: the squeeze is on buildings that already exist
SGV industrial vacancy tightened to 5.4% in Q2 2026, down from 6.0% the previous quarter, and net absorption swung to positive 1,205,159 SF after a reading of negative 1,065,324 the quarter before. Asking rents moved from $15.00 at the end of 2025 to $16.44 PSF NNN per year, about $1.37 a foot per month.
The number that matters most is the one nobody quotes: 373,533 SF under construction against 178.1 million SF of inventory. That is two tenths of one percent. There is no relief coming from new supply, so every requirement over 20,000 feet is competing for a building that is already standing, and most of those are in City of Industry, which carries the majority of the Valley's leasing and sales volume. If you own one, you have more leverage this quarter than you had last quarter. If you need one, start earlier than you think you need to.
Office: the Valley is not Los Angeles, and Pasadena is not the Valley
San Gabriel Valley office ran 6.9% direct vacancy at $2.80 per foot in Q2 2026. Los Angeles County as a whole ran 16.4% at $3.50. Owners here are reading national office headlines that describe a market they are not in.
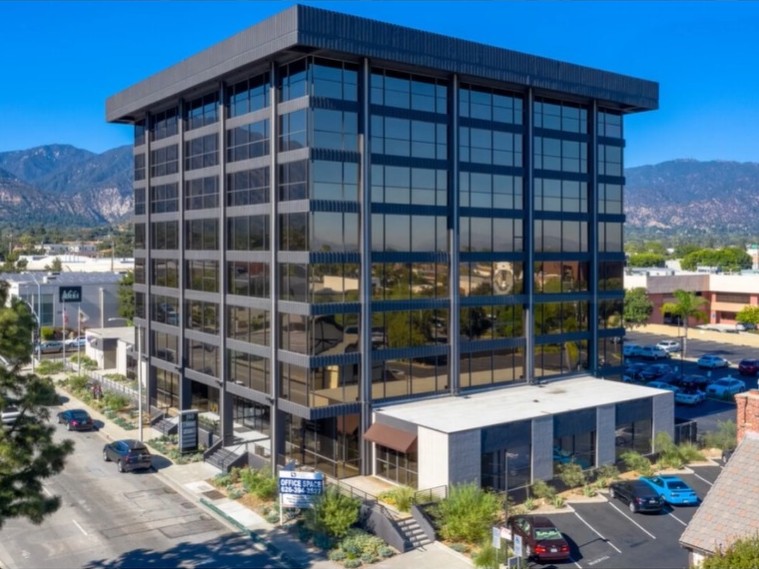
The split inside the region is just as sharp, and it is the thing I spend the most time explaining. Kidder Mathews report Pasadena as its own office submarket rather than folding it into the SGV, and the reason is visible in the numbers: Pasadena is 13.8% vacant at $3.57 a foot: double the Valley's vacancy and 77¢ dearer. For a tenant, that is a real decision rather than a rounding error. The office space I have at 150 N. Santa Anita Ave in Arcadia asks $2.90 with 1,000 to 11,000 SF available: ten cents over the SGV average and 67¢ under Pasadena, and three and a half miles down Huntington Drive from the Pasadena suites above. Lease structures differ, so the comparison is a starting point rather than a like-for-like, but the gap is wide enough to survive the caveat.
Retail: the average is not the deal
SGV retail vacancy was 5.10% in Q1 2026 with average asking rents easing to $33.81 PSF NNN and regional sale pricing at $370 per foot on a 6.00% cap. National tenants are still committing: Crate & Barrel took 17,283 SF on North Fair Oaks in Old Pasadena and Fogo de Chão 19,700 SF in West Covina.
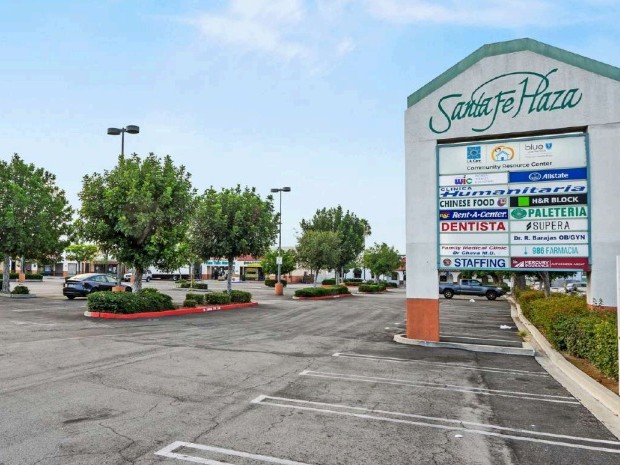
What the average hides is how far corridor quality moves pricing. A single-tenant building at 632 S. San Gabriel Blvd traded at $710 per foot; a multi-tenant center in West Covina went at $551. My own listing at 3560 Santa Anita Avenue in El Monte (Santa Fe Plaza, 45,304 SF at $16,500,000) pencils to roughly $364 a foot, which is within six dollars of the regional multi-tenant average. That is the arithmetic I want an investor doing before we talk about cap rate, because a center priced on the region and a pad priced on the corner are not the same asset.
Sources: Lee & Associates, LA - San Gabriel Valley Industrial Market Overview, Q2 2026 and Retail Market Overview, Q1 2026; Kidder Mathews, Los Angeles Office Market Report, Q2 2026 (rates quoted per month, full service). Figures are deemed reliable but not guaranteed and move every quarter.